
Automotive retail dynamics have shifted rapidly, leaving buyers who rely on traditional dealership financing vulnerable to inflated interest margins, predatory ancillary products, and prolonged loan tenures that create severe negative equity traps. Mastering auto acquisition and loan restructuring requires an adversarial understanding of dealership finance offices and secondary credit markets.
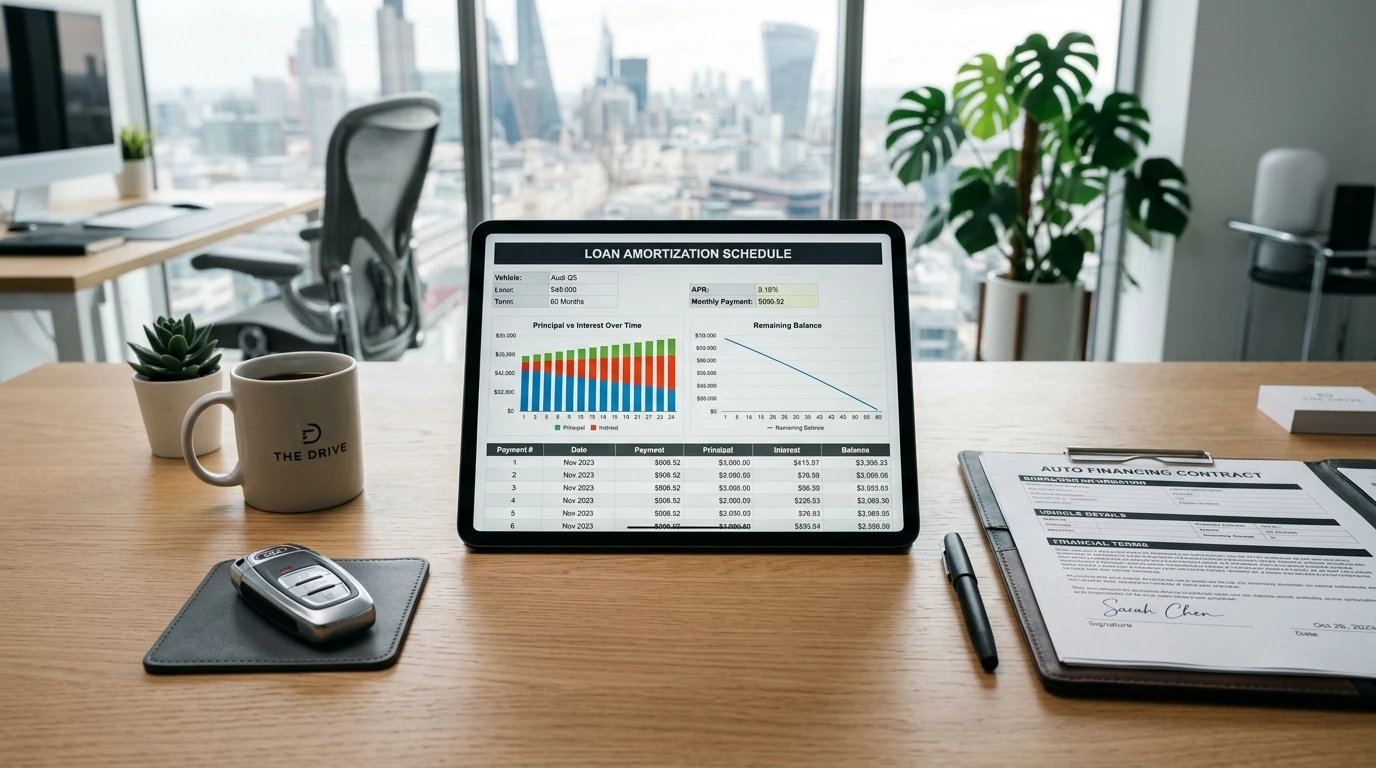
Whether navigating the purchase of a new EV, securing a reliable late-model certified pre-owned vehicle, or refinancing an existing high-APR auto note, deploying programmatic financing strategies yields thousands of dollars in direct interest savings and protects asset liquidity over the ownership cycle.
Strategic Pillars for New and Pre-Owned Acquisitions
- Decouple Purchase Price from Financing and Trade-In Negotiations: Dealerships maximize profitability through the "four-square" method, blending trade value, down payment, monthly payment, and purchase price to obscure margin expansion. Treat these as three strictly isolated transactions. Finalize the Out-The-Door (OTD) purchase price in writing before introducing trade-in documentation or discussing credit terms.
- Arrive with Institutional Direct Lending Pre-Approvals: Secure loan approvals from national credit unions and regional commercial banks prior to dealer contact. Dealerships often add a discretionary finance reserve (often 100 to 250 basis points) onto wholesale buy rates offered by captive lenders. Holding an independent approval forces the Finance & Insurance (F&I) manager to beat your baseline rate or forfeit origination revenue entirely.
- Audit the Buyer’s Order for Phantom Line-Item Markups: Dealer processing fees, dealer preparation charges, nitrogen tire fills, security etching, and paint sealant protection packages represent non-essential, pure-profit line items. Demand that these items either be deleted from the final bill of sale or offset via a dollar-for-dollar reduction in the vehicle’s base price.
- Execute Month-End and Quarter-End Inventory Arbitrage: Dealerships operate under floorplan financing models where holding aged inventory incurs daily carrying costs. Targets shift dramatically during the final 72 hours of calendar quarters. Leverage multi-dealer bidding across digital sales departments within a 200-mile radius to extract aggressive unit-turnover discounts on existing lot inventory.
Pro Tactics for Auto Loan Refinancing
Refinancing is not merely a reactive tool for distressed borrowers; it is an aggressive wealth-preservation tactic. When interest rate benchmarks adjust or credit scores cross key underwriting tiers (such as shifting from subprime to prime, or prime to super-prime), restructuring outstanding vehicle debt unlocks immediate cash flow.
- The 90-Day Credit Optimization Sprint: Prior to applying for refinancing, drive down revolving credit utilization below 7% across all personal cards and resolve disputed inaccuracies on credit files. Moving your auto-specific FICO score across a single scoring bracket can reduce an interest rate by 300 to 600 basis points.
- The Amortization Truncation Maneuver: When refinancing to a lower annual percentage rate, resist the temptation to extend the loan term back to 60 or 72 months to lower the monthly payment. Instead, match the new term to the remaining life of the original loan—or contract it further to 36 or 48 months. This channels the rate reduction directly into accelerated principal reduction.
- Loan-to-Value (LTV) De-Risking: Lenders reserve their lowest refinancing rates for notes with an LTV under 80% to 90%. If depreciation has pushed your loan balance close to or beyond market retail value, deploy a small capital lump sum to bring the loan-to-value ratio into Tier 1 parameters, qualifying the balance for institutional-grade rates.
- Ancillary Product Proration and Cancellation: If refinancing replaces an existing contract loaded with dealer GAP insurance, extended warranties, or prepaid service maintenance, formally execute cancellation forms with the original administrators. You are legally entitled to a prorated refund of the unearned balance, which is directly credited against your outstanding principal balance before the new payoff quote is generated.
Advanced Optimization Shortcuts and Expert Tweaks
Experienced operators leverage structural financing loopholes to maintain capital control:
- Bifurcated Down Payment Deployment: Instead of surrendering a large cash down payment to a dealer at closing, retain that capital in an interest-bearing liquidity reserve and finance the maximum permissible amount at a promotional, sub-vented rate (e.g., manufacturer 0.9% to 2.9% APR). The interest yield from low-risk sovereign cash equivalents often outpaces the nominal cost of subsidized borrowing.
- Bi-Weekly Amortization Automation: Split monthly auto payments into two equal bi-weekly debits via automated loan servicing portals. This results in 26 half-payments annually (equaling 13 full monthly payments), accelerating principal paydown, shaving months off the loan maturity date, and suppressing compound interest accumulation.
- Cash-In Refinancing for Eliminating GAP Premiums: If paying down equity allows you to shed GAP insurance entirely, calculate the savings of self-insuring against total loss. Once vehicle equity crosses 20%, continuing to pay third-party GAP coverage yields zero net financial utility.
Rapid Efficiency Recap
Never negotiate a car purchase on monthly payment amounts; isolate the out-the-door price first, leverage competitive credit union pre-approvals to suppress captive lender markups, and strip unvetted add-ons from final documentation. For existing notes, monitor regional credit union balance sheet promotions, deploy targeted cash injections to capture optimal LTV tiers, and cancel old dealer warranties for immediate principal reductions. Treating vehicle transactions as precision capital allocations preserves equity and neutralizes structural retail friction.